TSP to Gold IRA Rollover for Federal Employees and Military
Generally, yes. The Thrift Savings Plan (TSP) says you can roll over part or all of a distribution to an IRA, and a Gold IRA is a self-directed IRA. Traditional TSP money goes to a Traditional IRA, Roth TSP money only to a Roth IRA. A direct rollover has no tax withheld.
The Thrift Savings Plan (TSP) is the retirement savings plan for federal civilian employees and members of the uniformed services. It is run by the Federal Retirement Thrift Investment Board (FRTIB). Some people with a TSP balance ask whether it can fund a Gold IRA. This page explains the rules. It does not say whether moving money is right for you. For the wider picture, see the Gold IRA Rollover Guide.
Can you move your TSP into a Gold IRA?
Generally, yes, if the TSP money is paid out in a way that can be rolled over. A "Gold IRA" is a self-directed IRA whose custodian allows physical precious metals. The TSP's own rollover fact sheet says participants may roll over eligible distributions to "a qualified trust or an eligible retirement plan," and IRAs are among the destinations (TSP fact sheet). The TSP's distribution booklet adds a caution: "Check with the IRA provider or the other plan's administrator to see if it can accept your rollover" (TSP Distributions booklet). So ask the Gold IRA custodian before you start.
Two things decide what is possible: whether you are still in federal service, and what kind of money is in the account.
Can you move TSP money while still working?
The TSP offers two in-service withdrawals: an age-based withdrawal and a financial hardship withdrawal (TSP).
- Age-based (59½) withdrawals. You must be at least 59½. The TSP says you can make up to four per calendar year, and each must be at least $1,000 (or your entire vested balance). It says you "may be able to roll over all or part" of one to a traditional IRA or an eligible employer plan, depending on whether the money is traditional or Roth and what kind of account receives it (TSP booklet on in-service withdrawals).
- Hardship withdrawals. The IRS lists hardship withdrawals among payments that can't be rolled over (IRS). I did not find the TSP booklet addressing this point, so confirm with the TSP.
After you leave federal service, the TSP lists partial distributions, a total distribution, installments and annuity purchase. You can combine them. A partial distribution must be at least $1,000 (TSP). The booklet says you can roll over part or all of a partial or total distribution, or eligible installments, to an IRA or eligible employer plan.
Other plans have their own in-service rules. For a general look, see in-service rollovers.
Which form do you use? What about Form TSP-70?
Older guides often point to Form TSP-70 for a full withdrawal after separation. The TSP's current forms and resources page does not list it. That page says "You don't need to complete a paper withdrawal form" (TSP forms page). The current distributions booklet tells participants to log in to My Account on tsp.gov, or call the ThriftLine, to start a request (TSP Distributions booklet).
Those pages may change. Before you act, check tsp.gov or call the TSP to confirm how requests are made today. If a Gold IRA firm hands you a paper form with a TSP form number, ask the TSP whether it is still in use.
How do you roll TSP money into a Gold IRA?
The steps below follow the TSP and IRS sources cited on this page. The order is a general outline, not advice.
| Step | Who | What to confirm |
|---|---|---|
| 1. Check eligibility | TSP (My Account or ThriftLine) | Are you able to take a withdrawal now? Which kinds of money (traditional, Roth, tax-exempt) are in the payment? |
| 2. Open the self-directed IRA | A custodian that holds precious metals | Does it accept TSP rollovers? What is the exact payee name and mailing address? What are all fees? |
| 3. Match account types | You, with the custodian | Traditional TSP money to a Traditional IRA. Roth TSP money to a Roth IRA. |
| 4. Request a direct rollover | TSP | Ask that the payment go to the IRA custodian, not to you. |
| 5. Confirm receipt | The custodian | Has the full amount arrived and been coded as a rollover? |
| 6. Buy eligible metal | You, a dealer and the custodian | Is the product IRA-eligible? What are the total cost and the buyback terms? Where will it be stored? |
| 7. Keep records | You | Save TSP statements, any Form 1099-R and custodian confirmations. |
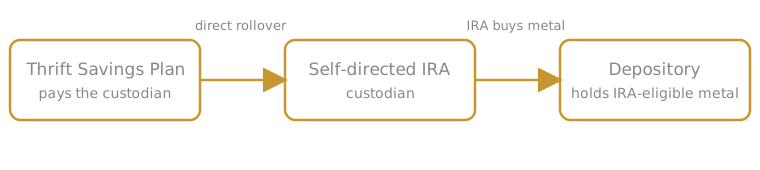
The TSP says rollovers are "made daily by the issuance of a U.S. Treasury check to the destination plan or IRA" (TSP fact sheet). The IRS describes the direct method as asking "your plan administrator to make the payment directly to another retirement plan or to an IRA" (IRS).
What happens if the TSP pays you instead?
If the payment goes to you, the TSP says it must withhold 20% for federal income tax. It also says you have 60 days after getting the payment to do the rollover (TSP tax rules booklet). The IRS says the 20% applies "even if you intend to roll it over later," and that if tax was withheld you need other money to roll over the full original amount (IRS).
| Direct rollover | Payment to you, then rollover | |
|---|---|---|
| Who receives the money | The IRA custodian | You |
| Federal tax withheld | None (per the IRS) | 20% (per the TSP) |
| Deadline | None for you to meet | 60 days |
| Full amount rolled over | Nothing extra needed | You replace the withheld 20% from other money |
| If you miss it | Lower risk | The part not rolled over is taxable and the 10% additional tax may apply |
For example, on a $50,000 payment to you, $10,000 would be withheld and you would receive $40,000. To roll over all $50,000, you would deposit the $40,000 plus $10,000 of other money within 60 days. This is an illustration only. The mechanics are explained in direct vs indirect rollovers and the 60-day rollover rule.
What about Roth TSP money?
The TSP's Roth balance has its own rules.
- Mixed accounts. If your account holds both traditional and Roth money, the TSP says distributions are paid proportionally from each balance, and the two parts are distributed and rolled over separately. You can ask for a distribution from just one balance (TSP fact sheet).
- Where Roth money can go. The fact sheet says an eligible retirement plan for a Roth distribution "includes only a Roth account maintained by an eligible employer plan or a Roth IRA." So Roth TSP money can't be rolled into a Traditional IRA.
- Pre-tax money into a Roth IRA. The IRS rollover chart marks a pre-tax plan rolling to a Roth IRA with a note: "Must include in income" (IRS chart). That is a taxable conversion, not a tax-free rollover. The chart does not name the TSP, so ask a tax professional how it applies.
- The five-year clock. The TSP says that after a rollover to a Roth IRA, the starting date for the 5-year rule for qualified distributions "does not carry over" (TSP tax rules booklet).
Roth rules have a lot of detail. See Roth conversions for background.
What can't be rolled over?
The IRS lists payments that can't be rolled over, including required minimum distributions, hardship withdrawals and loans treated as distributions. The TSP booklet likewise lists required minimum distributions and automatic enrollment refunds (TSP). The TSP fact sheet also says some receiving plans may reject tax-exempt money, such as contributions from military combat zone pay, and in that case "the tax-exempt portion of an intended rollover will be paid directly to the participant." Ask the TSP and your custodian how any tax-exempt balance will be handled.
Does leaving the TSP change the early-withdrawal rules?
Possibly. The TSP booklet says the 10% additional tax on early payments generally applies before age 59½, with exceptions. One is payments made after you separate from service "during or after the year you reach age 55" (TSP). We did not confirm from the sources opened here how that exception applies once money has moved from the TSP to an IRA. This is a question for a tax professional before you move money you may need before 59½. Our 401(k) to Gold IRA page covers the same exception for 401(k) plans.
What rules apply after the money is in the IRA?
The IRA, not the TSP, now sets the rules. The IRS says an account that acquires a collectible is treated as receiving a distribution in the year of acquisition, generally for the item's cost. Exceptions include certain coins described in 31 U.S.C. 5112 and bullion "of a certain fineness if a bank or approved non-bank trustee keeps physical possession of it" (IRS). See Gold IRA rules. A Gold IRA also brings custodian, storage and dealer costs, and metal prices can fall. The TSP itself warns that an in-service withdrawal "can have a serious impact on your ability to accumulate enough savings to support your future goals" (TSP).
Common mistakes
- Taking payment to yourself when a direct rollover was possible, which triggers 20% withholding.
- Sending Roth TSP money toward a Traditional IRA.
- Assuming an old form number is still current without checking tsp.gov.
- Not asking the custodian first whether it accepts TSP rollovers.
- Moving money before learning how the early-withdrawal exceptions apply to you.
Related questions
What about a 457(b) or a pension?
Other government and employer plans have their own rules. See 457 to Gold IRA rollover and pension lump sum to Gold IRA.
Do I have to roll over my whole TSP account?
No, not according to the TSP. A partial distribution must be at least $1,000, and the TSP says you can roll over part or all of a partial or total distribution (TSP).
Where should I ask questions?
Ask the TSP (My Account or ThriftLine) about its process. Ask the IRA custodian what it accepts. For taxes, talk to a CPA or enrolled agent.
Sources
- Withdrawals in retirement, Thrift Savings Plan (FRTIB). Accessed Invalid Date.
- Taking money from your account, Thrift Savings Plan (FRTIB). Accessed Invalid Date.
- Forms and resources, Thrift Savings Plan (FRTIB). Accessed Invalid Date.
- Rollovers from the Thrift Savings Plan to Eligible Retirement Plans (TSPFS05), Thrift Savings Plan (FRTIB). Accessed Invalid Date.
- Tax Rules about TSP Payments (TSPBK26, 4/2026), Thrift Savings Plan (FRTIB). Accessed Invalid Date.
- Withdrawals In-Service (TSPBK12, 5/2024), Thrift Savings Plan (FRTIB). Accessed Invalid Date.
- Distributions (TSPBK25, 9/2026), Thrift Savings Plan (FRTIB). Accessed Invalid Date.
- Rollovers of retirement plan and IRA distributions, Internal Revenue Service. Accessed Invalid Date.
- Rollover chart, Internal Revenue Service. Accessed Invalid Date.
- Investments in collectibles in individually directed qualified plan accounts, Internal Revenue Service. Accessed Invalid Date.
This guide is general education, not personalized financial, tax or legal advice. See our financial disclaimer, editorial policy and advertising disclosure.